
On 16 June 2026, the Cabinet approved steps to include Thailand’s Global Minimum Tax, referred to domestically as Top-up Tax, within the scope of the Multilateral Convention on Mutual Administrative Assistance in Tax Matters (MAC). The Cabinet also approved Thailand’s participation in the Multilateral Competent Authority Agreement on the Exchange of GloBE Information (GloBE MCAA), enabling the automatic exchange of GloBE Information Returns with partner jurisdictions.
Thailand’s Emergency Decree on Top-up Tax B.E. 2567 was published in the Royal Gazette on 26 December 2024 and has applied from 1 January 2025. The Cabinet summary states that Thai constituent entities of multinational enterprise groups with total consolidated revenue of at least the Thai-baht equivalent of EUR 750 million are subject to the regime. The rules are designed to ensure an effective tax rate of at least 15 percent in each jurisdiction.
For the first fiscal year, the GloBE Information Return filing deadline is 18 months from the last day of the accounting period. For a calendar-year multinational group first in scope for the 2025 fiscal year, the Cabinet summary identifies June 2027 as the first GIR filing deadline in Thailand, and December 2027 as the expected first exchange of GIR information with partner jurisdictions.
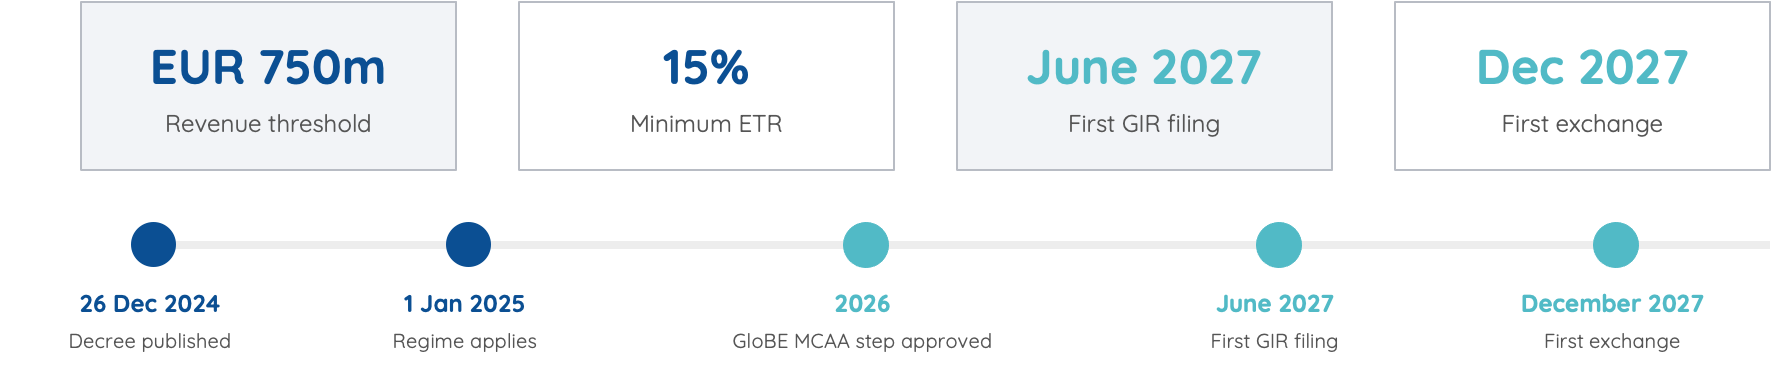
Figure 1. Thailand’s GloBE Implementation Timeline and Key Filing Milestones.
Legal and Commercial Analysis
This update is significant because it moves Thailand’s global minimum tax regime from domestic calculation to international transparency. Once the GloBE MCAA exchange begins, information filed in Thailand may be compared with information available to tax authorities in the ultimate parent jurisdiction and other constituent-entity jurisdictions.
The practical risk is inconsistency. GloBE calculations draw on financial accounts, covered taxes, jurisdictional effective tax rates, ownership structures, tax incentives and entity-level data. Inconsistent reporting between GIR, Country-by-Country Reports, statutory accounts, tax returns, BOI incentive records and transfer-pricing files may create audit exposure.
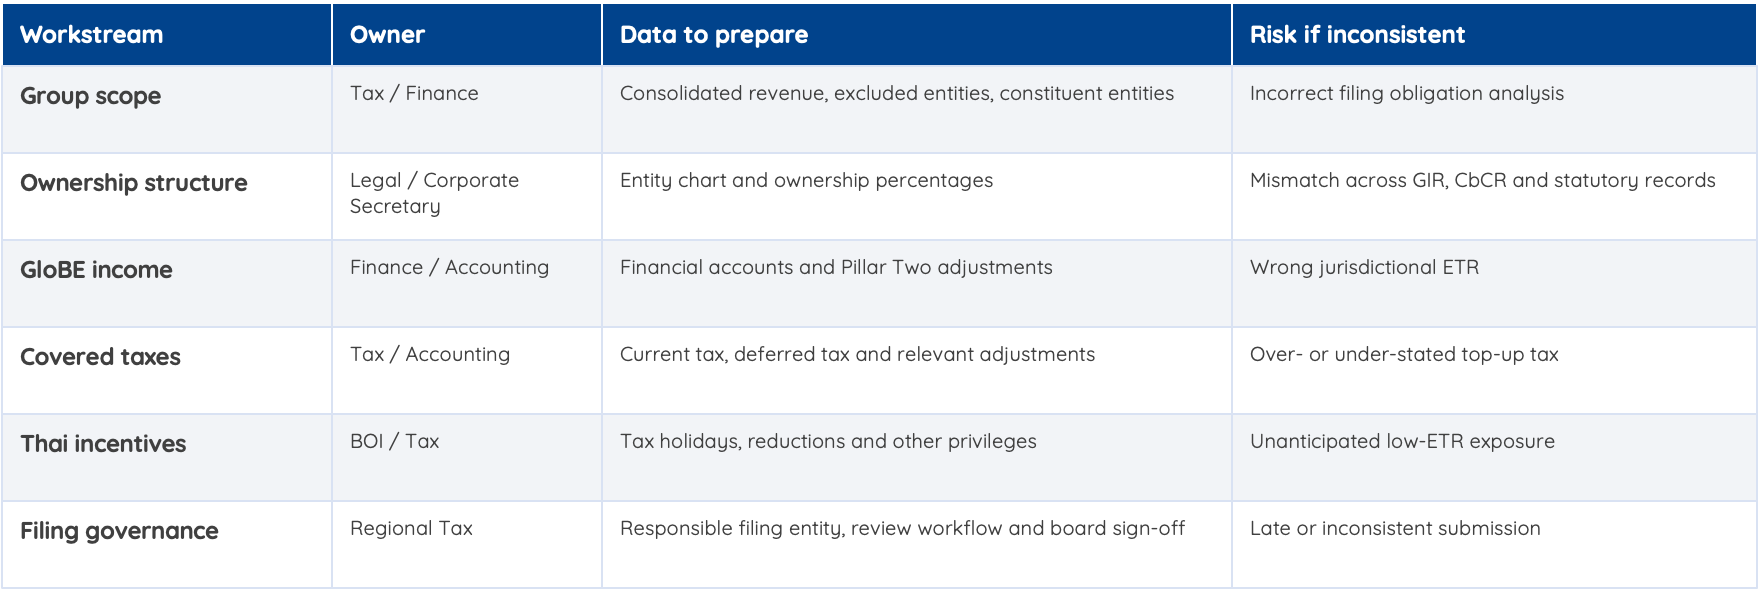
Figure 2. GloBE Readiness Workstreams and Data Consistency Risks.
BOI-promoted companies should pay particular attention. Tax holidays and preferential regimes can reduce local covered tax and affect the jurisdictional effective tax rate. The policy objective of the Top-up Tax is to preserve Thailand’s taxing rights where low-taxed profits arise in Thailand, rather than allowing another jurisdiction to collect the residual top-up tax.
Multinational groups should not wait until 2027. The first reporting cycle will require historical 2025 accounting-period data. Groups should determine which entity will coordinate the Thai GIR process, who owns the data, how information will be reconciled across jurisdictions, and how any top-up tax liability will be allocated within the group.
| Milestone | Timing |
| Top-up Tax Emergency Decree published | 26 December 2024 |
| Top-up Tax regime applies | 1 January 2025 |
| First in-scope fiscal year for calendar-year groups | 2025 |
| First GIR filing for first fiscal year | June 2027 |
| First GloBE MCAA information exchange | December 2027 |
Practical Client Action Points
✓ Confirm whether the multinational group meets the EUR 750 million consolidated revenue threshold.
✓ Identify all Thai constituent entities and reconcile legal ownership, accounting consolidation and tax registration data.
✓ Assess how Thai tax incentives, including BOI privileges, affect the jurisdictional effective tax rate.
✓ Prepare a GIR data workplan covering financial accounts, covered taxes, deferred tax, payroll, tangible assets and ownership information.
✓ Align Thai filings with group-level Pillar Two, CbCR, transfer-pricing and financial reporting teams.
This publication is provided for general informational purposes only and does not constitute legal, tax or professional advice. The analysis is based on official materials and reliable public sources available as of 10 July 2026. Readers should seek advice based on their specific facts before taking action. For assistance, please contact Mahanakorn Partners Group (MPG) at [email protected].